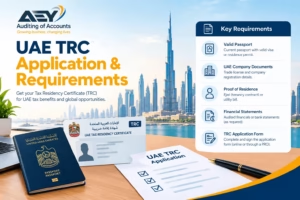
What Is an Individual UAE TRC?
An individual TRC is a certificate issued by the FTA that can be used as evidence of UAE tax residence for the requested purpose and period. It may be relevant to people dealing with foreign tax authorities or treaty claims.
Read our full UAE Tax Residency Certificate overview before you start your application.
Is 183 Days Required?
Not every individual case is reduced to a single 183-day shortcut. The FTA’s materials distinguish treaty and domestic purposes and describe more than one route for establishing UAE tax residence.
The FTA FAQ states a 183-day residence condition for a natural person during the required financial year.
The application flow distinguishes more than 183 days, 90–182 days, and less than 90 days — each with different evidence.
See our detailed guide on domestic vs tax treaty TRC purposes.
The 90-Day Route for UAE Tax Residence
A natural person who is present in the UAE for fewer than 183 days may still satisfy a 90-day test if additional conditions are met, including:
- Legal residence rights in the UAE
- A permanent place of residence or employment / business in the UAE
Evidence You May Need
Employees, Investors, Self-Employed and Retirees
The FTA manual gives different examples of source-of-income evidence depending on the applicant’s circumstances. Build the checklist around the actual case rather than copying a generic list.
What About People Who Spend Time Outside the UAE?
International mobility can make the evidence trail more important. Maintain travel records, residence evidence, income evidence and other documents that support the claimed period. The correct test depends on the application purpose and the facts of the applicant’s situation.
How to Apply
Frequently Asked Questions
Need Help With a UAE TRC Application?
AEY Auditing of Accounts can support applicants with eligibility review, document checking, application preparation and follow-up.
Talk to a TRC Specialist →Editorial note: Factual statements concerning FTA process, eligibility, documents, fees or timelines should be re-checked against the current FTA Tax Resident and TRC guide and FTA TRC Frontend User Manual 2025 before publishing.